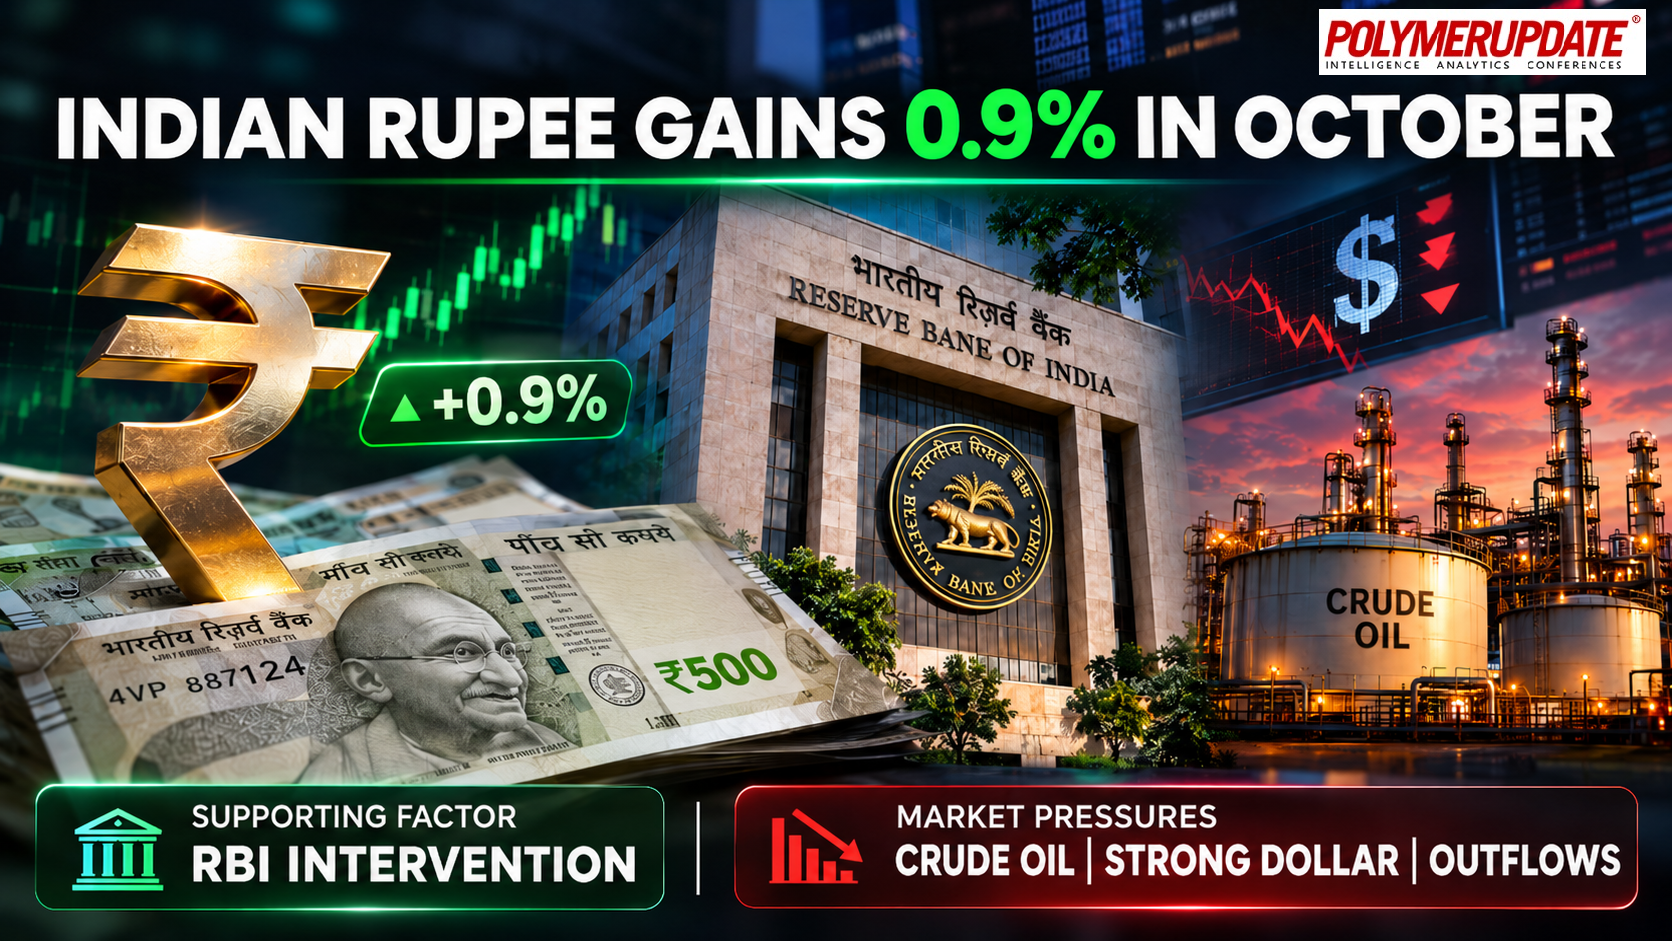
The Indian rupee demonstrated considerable resilience in October 2026, recovering from near-record lows to register a monthly gain despite mounting external pressures from elevated crude oil prices, rising global bond yields, a stronger US dollar and persistent foreign portfolio investor (FPI) outflows. Timely intervention by the Reserve Bank of India (RBI), including a series of measures to support the domestic currency and curb speculative trading, played a crucial role in containing the rupee's depreciation and restoring some stability to the foreign exchange market.
The rupee began October on a weak footing, trading precariously close to its lifetime low as India's external sector faced mounting challenges. During the first ten days of the month, the currency traded in a narrow but vulnerable range of Rs 96.32-96.74 against the US dollar, approaching its previous record low of Rs 96.83 against the greenback recorded in May 2026.
According to Aditi Gupta, Economist at Bank of Baroda, “Persistent foreign investment outflows, expensive crude oil imports and heightened uncertainty surrounding the Middle East conflict contributed to the currency's weakness. Global financial conditions also remained volatile, with spillover effects from geopolitical tensions pushing up international bond yields and strengthening the dollar.”
 Separate window for OMCs
With much of the pressure originating from external developments rather than domestic economic weakness, the RBI introduced special measures to prevent excessive volatility and support the rupee.
The central bank announced a separate dollar window for oil marketing companies (OMCs) to meet their foreign exchange requirements, alongside measures aimed at restricting speculative positions in the domestic currency market. These steps complemented its regular interventions in the spot and forward foreign exchange markets.
The measures triggered a notable recovery in the rupee. From Rs 96.74 versus US dollar on October 9, the currency strengthened to Rs 94.43 a dollar on October 21, appreciating approximately 2.4 percent over the period. The recovery reflected both the immediate impact of the RBI's intervention and a moderation in speculative pressure. However, the gains proved difficult to sustain as geopolitical tensions intensified and crude oil prices moved higher. Renewed concerns over the Middle East conflict prompted fresh demand for the dollar, while India's substantial dependence on imported energy continued to weigh on market sentiment.
Gain in OctoberDespite surrendering part of its recovery, the rupee ended October with a gain of approximately 0.9 percent against the dollar. Its performance was particularly noteworthy given that the US Dollar Index (DXY) strengthened during the month and several major emerging-market and advanced-economy currencies weakened against the greenback.
Among emerging-market currencies, the Brazilian real, Mexican peso and Taiwanese dollar registered declines, while the euro and Japanese yen also depreciated. The rupee's positive performance therefore highlighted the effectiveness of RBI intervention in cushioning the domestic currency against adverse international developments.
Conflicting external factorsSeveral factors influenced the rupee's movement during October, with RBI intervention, crude oil prices, foreign investment flows and movements in the dollar emerging as the principal drivers. Crude oil remained one of the most significant sources of pressure. Prices increased by more than 6 percent during October, averaging around US$ 108 a barrel amid escalating geopolitical tensions in the Middle East, including a significant intensification of hostilities involving Saudi Arabia and Yemen's Iran-aligned Houthi movement.
International crude prices subsequently climbed to around US$ 116 a barrel, their highest level in six months. For India, which imports approximately 85-88 percent of its crude oil requirements, sustained increases in energy prices translate into a higher import bill, additional demand for dollars and greater pressure on the current account balance. Another factor influencing the currency was the moderation in foreign portfolio outflows. Net FPI outflows declined to approximately US$ 2.5 billion in October from US$ 6.1 billion in September. This improvement was largely attributable to debt-market inflows, while equity outflows remained broadly stable.
Although the moderation offered some relief to the rupee, foreign investment flows continued to represent a source of vulnerability, particularly amid global risk aversion and attractive yields in international markets. The dollar also strengthened during the month, with the DXY rising 0.4 percent despite the US Federal Reserve keeping interest rates unchanged. Expectations of a possible rate hike in December 2026, alongside elevated US Treasury yields, supported the greenback and reduced the relative attractiveness of emerging-market currencies. These developments created an unfavourable external environment for the rupee, although RBI intervention helped offset some of the pressure.
Structural concernsBeyond short-term market movements, India's external-sector fundamentals will remain important in determining the rupee's medium-term trajectory. The merchandise trade deficit has widened compared with the previous financial year. During April-September 2026, the deficit increased to US$ 177.6 billion from US$ 156.9 billion in the corresponding period last year. Although export growth has been considerably stronger than in the previous year, imports have also increased, driven by higher oil-related expenditure and non-oil, non-gold imports. The increase reflects both elevated international commodity prices and resilient domestic demand.
With crude oil prices remaining above US$ 100 a barrel and uncertainty surrounding the resolution of the Middle East conflict persisting, India's merchandise trade deficit is likely to remain elevated in the coming months. However, stronger merchandise and services exports, together with resilient remittance inflows, are expected to provide some cushion against the deterioration in the trade balance. Consequently, the current account deficit (CAD) is projected to be higher than in the previous financial year, although it is expected to remain within a relatively comfortable range of 0.8-1 percent of GDP.
HeadwindsThe capital account, meanwhile, represents a more immediate source of concern. Persistent FPI outflows and increased repatriation of funds by foreign direct investors could weigh on India's capital account surplus. Furthermore, the scope for additional foreign currency inflows through the banking capital channel may remain limited following the closure of the FCNR (B) swap window. At the same time, the RBI may need to deploy a portion of the foreign exchange resources mobilised through earlier measures to support the rupee if elevated oil prices sustain demand for dollars.
India's foreign exchange reserves have also declined from their recent record levels. After touching an all-time high of US$ 785.7 billion on September 4, reserves fell to US$ 719.7 billion as of October 23, 2026. Although the reserve stockpile continues to provide a substantial buffer against external shocks, the decline underscores the pressures arising from currency intervention and movements in international capital flows.
OutlookLooking ahead, the rupee's near-term trajectory is likely to be influenced more by global financial conditions and market sentiment than by domestic macroeconomic fundamentals. Elevated crude oil prices, narrowing interest-rate differentials, continued risk aversion, FPI outflows and volatility in international bond markets are likely to remain key sources of depreciation pressure. The geopolitical situation in the Middle East will be particularly important. Any further escalation could push crude oil prices higher, increase India's import bill and intensify demand for dollars.
Conversely, meaningful progress towards de-escalation could ease energy prices and provide some relief to the domestic currency. The RBI's recent measures have provided timely support and demonstrated the central bank's commitment to ensuring that exchange-rate movements remain orderly and broadly range-bound. This policy support is likely to remain an important stabilising factor, provided there are no fresh external shocks. Nevertheless, intervention alone cannot permanently offset the impact of sustained increases in oil prices, a stronger dollar and persistent capital outflows.
Overall, Bank of Baroda expects the rupee to trade in the range of Rs 94.75-95.75 against the US dollar in the near term. While the currency has demonstrated resilience despite an adverse external environment, the sustainability of its recovery will depend considerably on international crude oil prices, global investor sentiment and the RBI's ability to contain excessive volatility.
DILIP KUMAR JHA
Editor
dilip.jha@polymerupdate.com