The Indian rupee came under renewed pressure in the early trade on Tuesday, briefly extending decline from two-month low level of 96.03 against the greenback touched yesterday, as elevated crude oil and gold prices heightened concerns over India’s external sector and the impact of the Middle East conflict on the country’s import bill. However, the Indian currency pared most of its losses later in the session as crude prices eased from their intraday highs and suspected central bank intervention helped limit the downside.
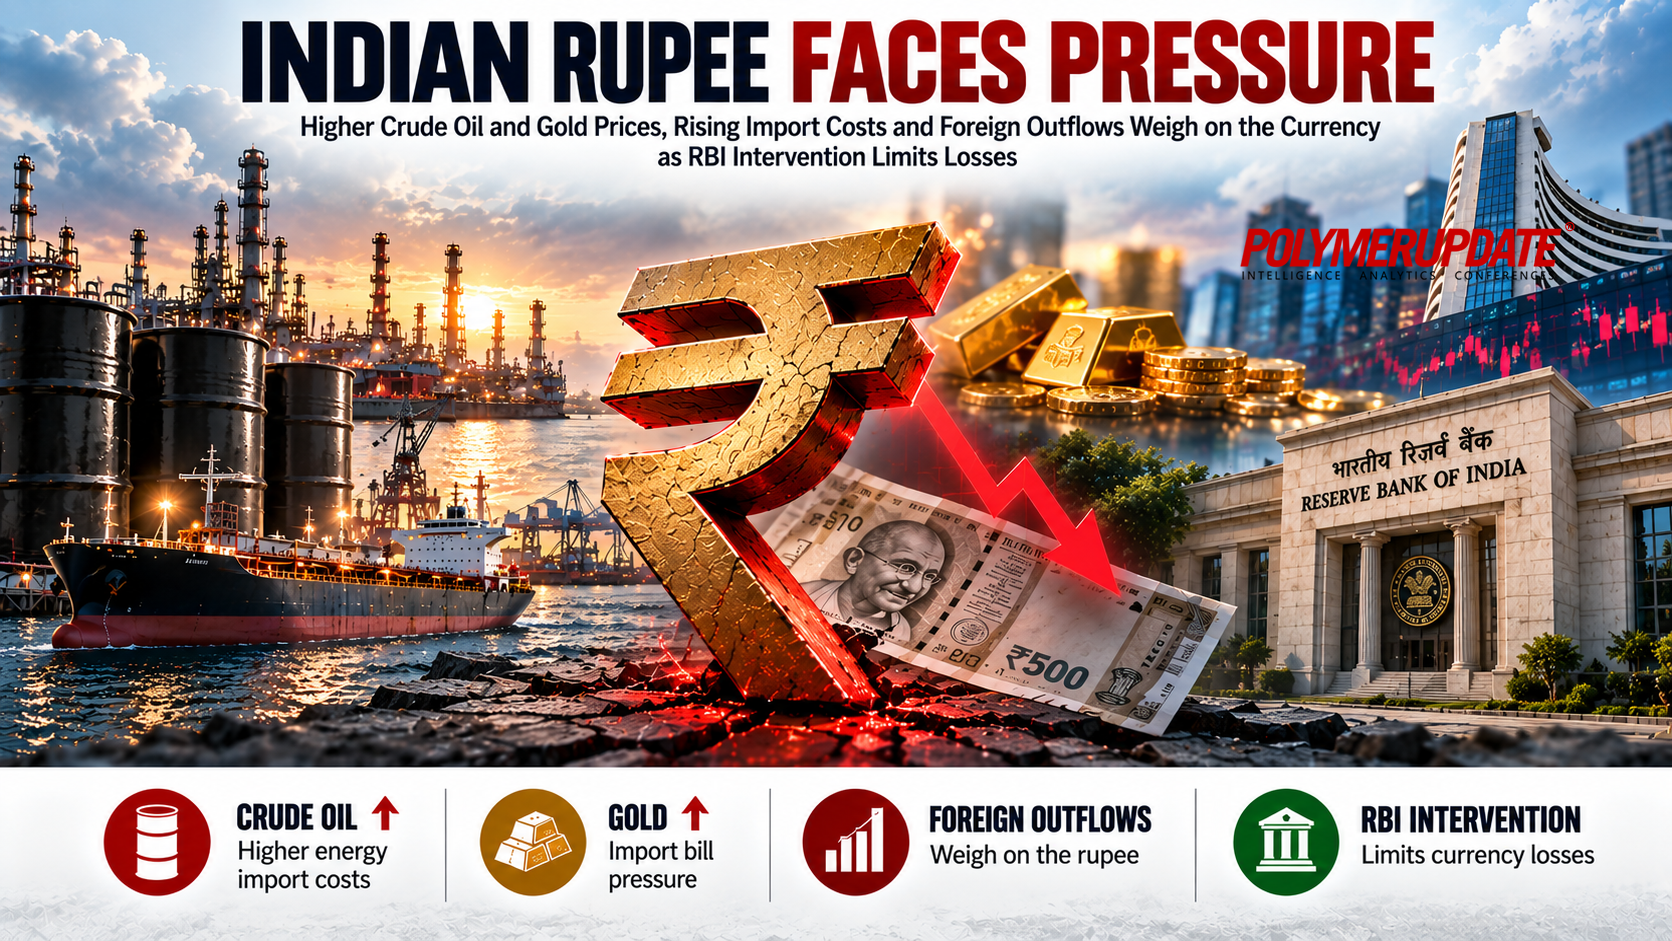
The rupee declined around 0.2 percent in early Tuesday to 96.1475 a dollar, and subsequently recovered to close almost unchanged at 95.98 a dollar as Brent crude prices turned lower after touching a peak of nearly US$ 108 a barrel. The Indian currency’s intraday movement once again highlighted the growing influence of crude oil prices on the rupee. India imports nearly 90% of its crude oil requirements, leaving the domestic currency particularly vulnerable to sharp increases in international energy prices. Any sustained rise in crude prices increases the country’s import bill, raises demand for dollars and can put pressure on the rupee.
 Strong oil-rupee link
The relationship between crude and the rupee has become especially important amid the continuing uncertainty surrounding oil supplies from the Middle East. With the region accounting for a significant share of global petroleum production and exports, any disruption to supply or shipping routes can quickly lift crude prices and increase the financial burden on large importing economies such as India. Higher oil prices affect the rupee through several channels. Apart from increasing the value of crude imports, expensive oil can widen India’s trade deficit and increase demand for foreign currency among refiners and other importers.
If the increase in the import bill persists, it can put additional pressure on the balance of payments and the domestic currency. The pressure on the rupee has also been compounded by weakness in domestic financial markets and foreign portfolio outflows. Foreign investors have withdrawn about US$ 3.7 billion from Indian equities and bonds so far in September, adding to the pressure on the currency. Foreign capital flows are an important component of the rupee’s short-term performance. When overseas investors sell Indian equities and debt, they generally repatriate the proceeds by converting rupees into dollars.
Such transactions increase dollar demand and can reinforce the downward pressure created by a higher oil import bill. The simultaneous pressure from crude prices and foreign capital outflows therefore presents a challenging environment for the rupee. While India’s domestic economic fundamentals remain an important medium-term factor, currency movements in the near term are likely to remain heavily influenced by developments in global oil markets and investor sentiment.
Swelling oil import billData compiled by the Ministry of Commerce & Industry showed that India’s crude oil import bill rose 26 percent year-on-year (yoy) to US$ 49 billion during April-June 2026, despite an 18 percent decline in import volumes amid supply disruptions caused by the conflict in West Asia and higher global crude prices. India imported 59.7 million tonnes (MT) of crude oil during the April-June quarter, compared with 73 MT in the corresponding period of 2025. Consequently, the lower import volume failed to offset the impact of elevated international oil prices, with the import bill rising sharply from US$ 39 billion a year earlier to US$ 49 billion during the latest quarter.
According to Petroleum Ministry data, India, the world’s third-largest crude oil importer, meets around 88 percent of its annual crude oil consumption through imports, leaving the economy highly exposed to movements in international oil prices and the rupee-dollar exchange rate. Any sustained increase in crude prices can significantly raise the country’s import bill, widen the trade deficit and increase demand for dollars, thereby putting pressure on the rupee. The latest data underscore the vulnerability of India’s external sector to geopolitical disruptions in major oil-producing regions, particularly when higher crude prices coincide with currency weakness.
Gold rushAnother factor contributing to pressure on the Indian rupee was the sharp rise in the country’s gold import bill. According to the Finance Ministry, India’s gold import bill surged 47.1 percent year-on-year to US$ 11.01 billion during the April-June 2026 quarter, compared with US$ 7.5 billion in the corresponding period of the previous year. The increase came despite the government raising the import duty on gold from 6 percent to 15 percent on May 13. Higher international gold prices also contributed significantly to the increase in the value of imports, adding to dollar demand and exerting additional pressure on the domestic currency.
Imports of gold from the UAE more than doubled to US$ 3.14 billion during the quarter, partly driven by a 1 percent tariff advantage available under the bilateral free trade agreement. Gold imports remained elevated despite the higher domestic import duty, reflecting sustained domestic demand and a shift in trade corridors. The sharp increase in gold imports, alongside the higher crude oil import bill, added to India’s overall demand for foreign currency and further complicated the external-sector environment for the rupee.
RBI’s interventionThe rupee’s recovery from Tuesday’s low also suggests that market participants continue to watch for intervention by the Reserve Bank of India. The central bank has historically intervened in the foreign exchange market to smooth excessive volatility rather than defend a particular exchange-rate level. Such intervention can help moderate sharp intraday movements, although sustained pressure from a widening import bill or persistent capital outflows can make it more difficult to prevent gradual currency depreciation.
The direction of crude prices is therefore likely to remain a key trigger for the rupee in the coming sessions. A further escalation in the US-Iran conflict, renewed attacks on energy infrastructure or disruptions around critical Middle Eastern supply routes could push crude prices higher and increase pressure on the Indian currency. Conversely, any credible progress towards a settlement between Washington and Tehran, improvement in the security situation or further recovery in regional crude exports could reduce the risk premium in oil prices.
A sustained decline in Brent prices would ease concerns over India’s import bill and could provide some relief to the rupee. The impact of crude prices extends beyond the foreign exchange market. Expensive oil can raise transportation, manufacturing and logistics costs and complicate the inflation outlook. It can also affect corporate margins, household purchasing power and the government’s broader economic policy calculations.
OutlookGoing forward, the rupee is likely to remain volatile and closely linked to developments in crude oil, Middle East supply flows and foreign investor activity. A sustained moderation in oil prices and improvement in global risk sentiment could ease pressure on the currency, while another sharp increase in crude or continued foreign portfolio withdrawals could renew selling pressure. For the Indian currency, therefore, the immediate outlook will depend not only on domestic economic indicators but also, importantly, on events unfolding thousands of kilometres away in the Middle East.
DILIP KUMAR JHA
Editor
dilip.jha@polymerupdate.com