The global plastics industry is entering a new phase of expansion, with the market expected to surpass US$1 trillion in value in 2026, supported by rising demand from packaging, construction, automotive, healthcare and other industrial applications. According to Grand View Research, the global plastics market was valued at US$ 963.7 billion in 2025 and is projected to increase to US$ 1,009.7 billion in 2026 and reach US$ 1,361.3 billion by 2033, registering a compound annual growth rate (CAGR) of 4.4 percent between 2026 and 2033, a report from Grand View Research showed.
Market estimates vary significantly depending on the definition and scope of the plastics industry. Broader classifications covering plastics, polymers and related chemical products place the 2026 market value at around US$ 1 trillion, while narrower estimates covering core polymer production and selected segments put the value at approximately US$ 560 billion-US$ 580 billion. Despite these differences, the estimates point to a common trend: global demand for plastics is continuing to expand, particularly across emerging economies.
 Production
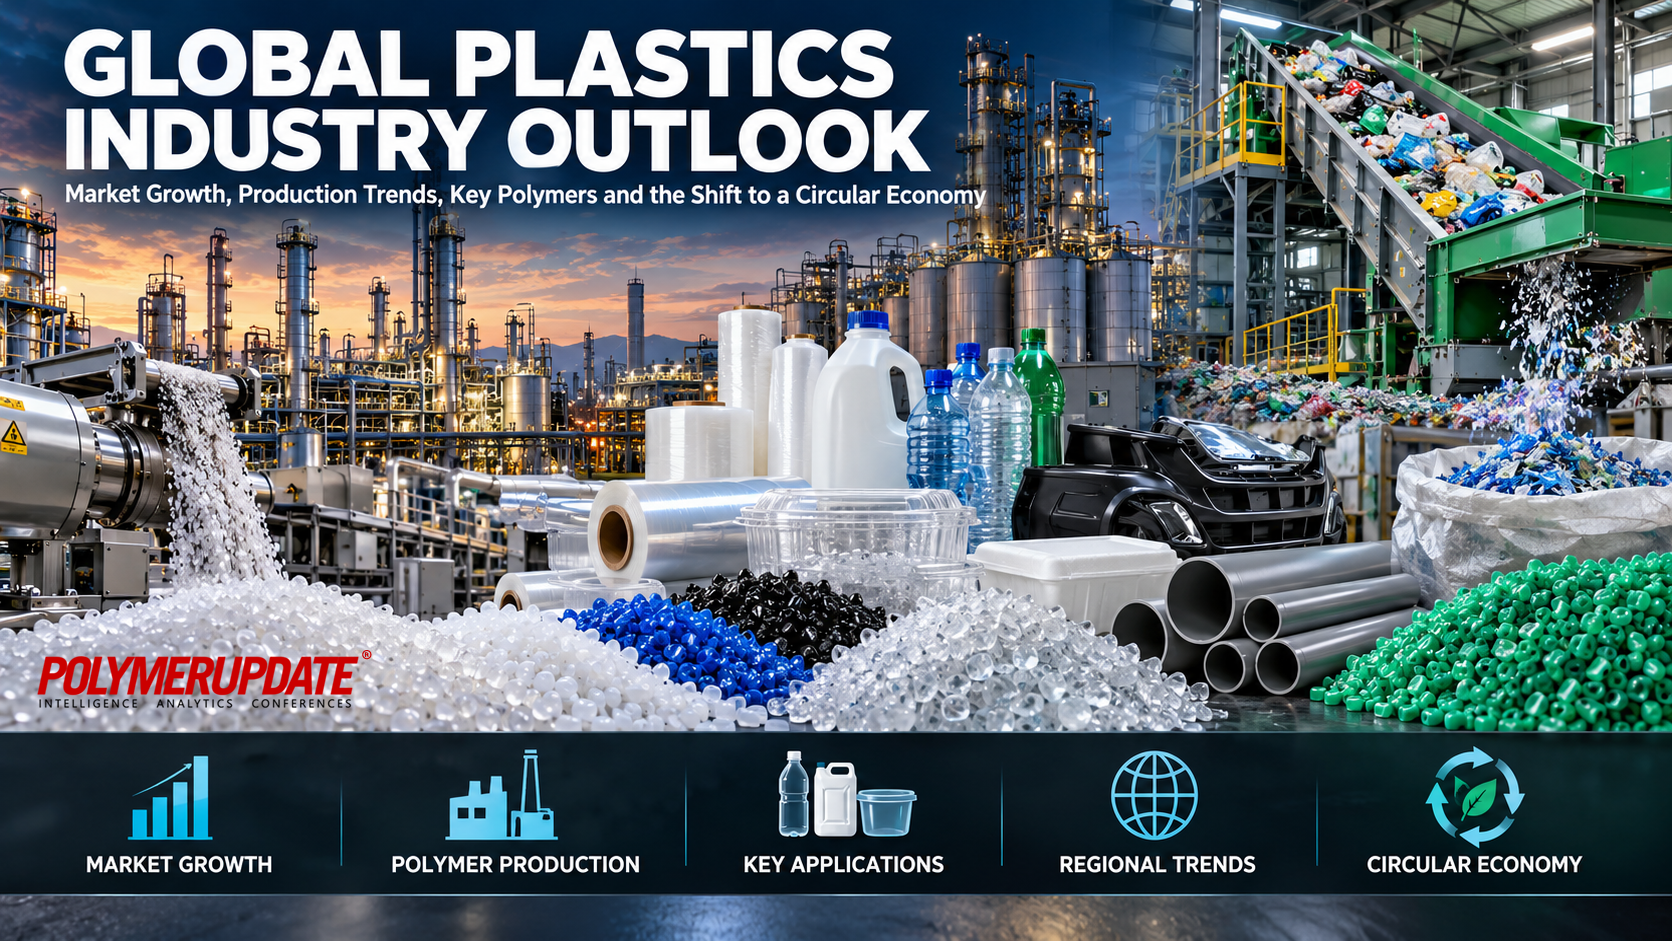
Global plastic production has already exceeded 430.9 million tonnes annually, highlighting the scale of the industry and its importance to manufacturing and consumer markets. Demand is being supported by the lightweight, durable, versatile and cost-effective characteristics of plastics, which have enabled their widespread use across a broad range of applications.
Asia Pacific remains the dominant regional market and is expected to continue driving global industry growth. Grand View Research estimates that the region accounted for 45.9 percent of global plastics market revenue in 2025. Other estimates based on production and consumption measures place the region's share considerably higher, at around 53-61.6 percent. The region's dominance is primarily attributable to rapid industrialisation, expanding manufacturing capacity, rising consumer demand and increasing investments in infrastructure. China and India are at the centre of this expansion, with both countries emerging as major producers and consumers of polymers and finished plastic products.
A report from For Insights Consultancy reads, “The global plastic and polymers market continues to witness steady expansion driven by strong demand from packaging, automotive, construction, and consumer goods industries. Rapid urbanization and industrial development are accelerating the need for lightweight and durable materials. Emerging economies are playing a major role in boosting manufacturing activities. Technological advancements in polymer processing are further enhancing product performance and efficiency.”
China – the biggest producerChina remains the world's largest individual plastics-producing country, accounting for an estimated 31-34.5 percent of global production. Its enormous manufacturing base, integrated petrochemical industry and extensive downstream processing capacity have enabled the country to maintain its leading position in the global plastics value chain.
India, meanwhile, is becoming an increasingly important growth market as rising incomes, urbanisation, infrastructure development and expanding manufacturing activity stimulate demand for plastic products. The country's large population and growing consumer economy are expected to support sustained growth in packaging, automotive, consumer goods and construction-related applications.
North America is the second-largest major producing region, supported by extensive petrochemical feedstock availability and a highly developed polymer manufacturing industry. Plastic production in the United States exceeds 136 million tonnes, reflecting the country's substantial resin production and downstream manufacturing base.
Europe also remains an important contributor to global plastics production, although its industry is increasingly shaped by environmental regulations, recycling targets and the transition towards a circular economy. European plastic production is estimated at around 54.6 million tonnes.
Packaging remains the largest consumerPackaging continues to be the single largest end-use segment for plastics, accounting for roughly 36-40 percent of total demand, depending on the market definition and methodology used. The sector benefits from plastics' combination of low weight, strength, durability, barrier properties and relatively low production costs. The continued expansion of food delivery, e-commerce, packaged food and beverages, pharmaceuticals and consumer goods is supporting demand for flexible and rigid plastic packaging.
At the same time, sustainability concerns are pushing manufacturers towards recyclable, reusable and recycled-content packaging solutions. Beyond packaging, construction remains a major source of demand for plastics, particularly for pipes, insulation, flooring, roofing, profiles and other building applications. Plastics are also gaining importance in the automotive sector because their lightweight characteristics can help manufacturers reduce vehicle weight and improve fuel efficiency. The transition towards electric vehicles is creating additional opportunities for plastics and engineering polymers.
Lightweight materials are increasingly being used in vehicle interiors, exteriors, battery components, electrical systems and other applications as automakers seek to improve vehicle efficiency and optimise battery performance. Healthcare represents another important growth segment, with plastics widely used in medical packaging, syringes, diagnostic equipment, tubing, protective equipment and a variety of disposable and durable medical products.
PE remains the leading polymerAmong major polymer categories, polyethylene (PE) continues to command the largest share of the global market. Grand View Research estimates that the PE segment accounted for 24.8 percent of the market in 2025. PE's leading position is supported by its extensive use in packaging films, containers, pipes, household products and industrial applications. Polypropylene (PP) is another major polymer, benefiting from strong demand in packaging, automotive components, appliances, consumer goods and healthcare applications.
Polyvinyl chloride (PVC) remains particularly important in construction, where it is used extensively in pipes, profiles, cables, flooring and other building products. Polyethylene terephthalate (PET), meanwhile, continues to benefit from demand for beverage bottles, food packaging, films and other applications. The diversity of applications across these polymers provides the plastics industry with a broad demand base and reduces its dependence on any single downstream sector.
Injection moulding drives processing demandFrom a processing perspective, injection moulding represents the largest application segment, accounting for around 42 percent of the market in 2025, according to the estimates provided by Grand View Research. Injection moulding is widely used because it can produce large volumes of complex components with consistent quality and relatively low unit costs. The process is extensively employed in automotive components, consumer products, electrical and electronic equipment, packaging, appliances and healthcare products.
The growth of advanced manufacturing, automation and lightweight components is expected to further support demand for injection-moulded products. Increasing adoption of engineering plastics and high-performance polymers is also expanding the range of applications available to processors.
Sustainability reshapes the industry's growth trajectoryDespite strong growth prospects, the global plastics industry faces increasing pressure to reduce its environmental footprint. Governments, regulators, brand owners and consumers are demanding higher recycling rates, greater use of recycled materials and reductions in plastic waste. This is accelerating investment in mechanical recycling, chemical recycling, advanced sorting technologies and circular business models.
The development of recycled polyethylene, polypropylene and PET is expected to become increasingly important as manufacturers seek to comply with regulatory requirements and meet sustainability commitments. The transition towards a circular plastics economy is therefore likely to reshape the industry's investment priorities over the coming decade. Virgin polymer demand is expected to remain substantial, particularly in emerging markets, but recycled and renewable feedstocks are likely to account for a growing share of future production.
Positive outlookMajor global industry participants include ExxonMobil, BASF SE, Dow Inc., SABIC, LyondellBasell Industries and China National Petroleum Corporation. Their investments in polymer capacity, specialty materials, recycling and advanced applications are expected to influence the competitive landscape. Asia Pacific is likely to remain the centre of global plastics growth, while China will continue to dominate production. India and other emerging economies, meanwhile, are expected to provide significant incremental demand as industrialisation, urbanisation and consumer spending increase.
Overall, the plastics industry's growth story remains closely linked to the expansion of the global economy. While sustainability regulations and changing consumer preferences are forcing the industry to evolve, the combination of cost efficiency, lightweight properties, durability and versatility continues to underpin demand. The challenge for producers and processors will increasingly be to capture this growth while simultaneously reducing waste, improving recyclability and moving towards a more circular plastics economy.
DILIP KUMAR JHA
Editor
dilip.jha@polymerupdate.com